Travel Planning Guide
Is Trip Cancellation Coverage Worth The Cost
A practical way to weigh what you have prepaid against what a policy actually promises to return.
Trip cancellation coverage is one of the most debated parts of travel planning, and the question of whether it is worth the cost rarely has a single answer. For some travelers, a policy is a small price for protecting a large prepaid vacation. For others, it is an extra expense that may never be used. Because policies differ in what they cover, what they exclude and how much they return, the value depends on the details of the trip, the traveler and the contract. This article lays out a framework for deciding, without relying on one-size-fits-all claims.
What Trip Cancellation Coverage Is Designed to Do
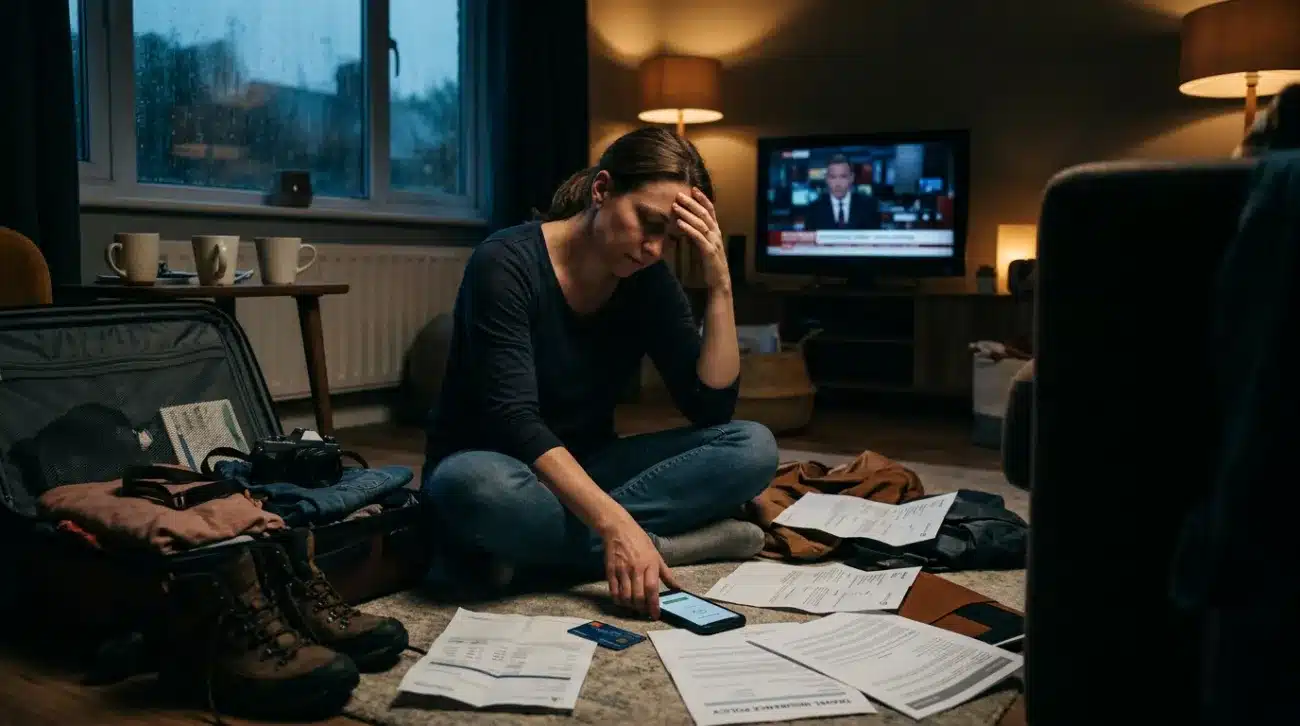
Trip cancellation coverage is a form of travel insurance intended to reimburse certain prepaid, nonrefundable trip costs if a traveler has to cancel for a reason the policy lists as covered. It is separate from other types of travel protection, such as emergency medical coverage or baggage coverage, even though insurers often bundle these features together in a single plan. The central idea is financial: you commit money weeks or months before departure, and the policy is meant to limit the loss if a listed event forces you to call the trip off.
What matters most is that the coverage is conditional. A policy does not generally return money simply because a traveler changes their mind. It responds to the reasons written in the contract, and those reasons are defined by the insurer. Two plans with similar names can therefore behave very differently when a claim is filed. Reading the policy document, rather than the marketing summary, is the only dependable way to know what you are buying.
Weighing the Cost of Travel Insurance Against What You Have Prepaid
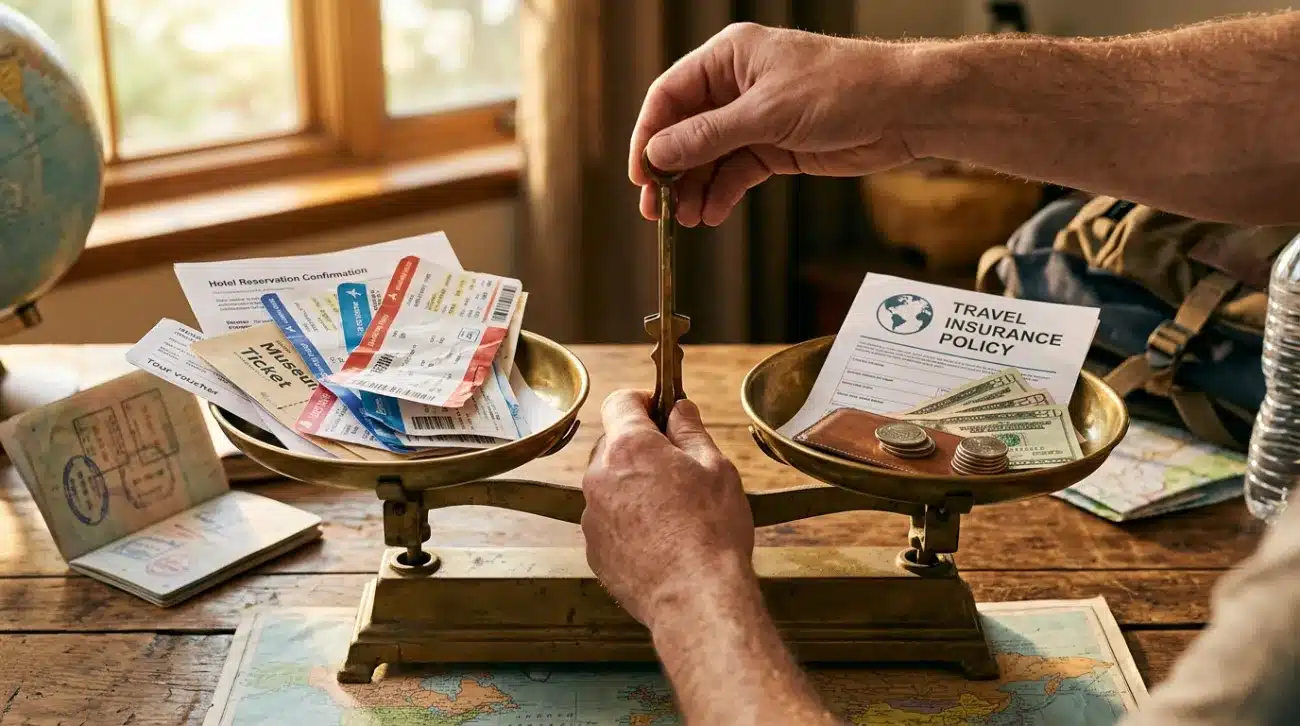
The simplest test of value compares the premium with the amount you stand to lose. If a trip is inexpensive, mostly refundable or easy to rebook, the money at risk is small, and a policy may add little. If a trip involves large nonrefundable deposits, flights, prepaid tours or a cruise fare paid in full, the amount exposed is larger and the argument for protection grows stronger. Insurance is fundamentally a trade: a known, modest cost now in exchange for reduced exposure to an uncertain, larger loss later.
Premiums usually respond to factors the insurer chooses, which commonly include the cost of the trip, the length of the journey and the traveler’s age, although each company sets its own pricing. Because quotes vary between providers and policy tiers, comparing several written quotes for the same itinerary is more reliable than relying on a general rule of thumb. It also helps to ask what portion of the trip cost the policy will actually insure, since only the nonrefundable, prepaid portion is normally at issue.
How Covered Reasons and Exclusions Shape Real Value
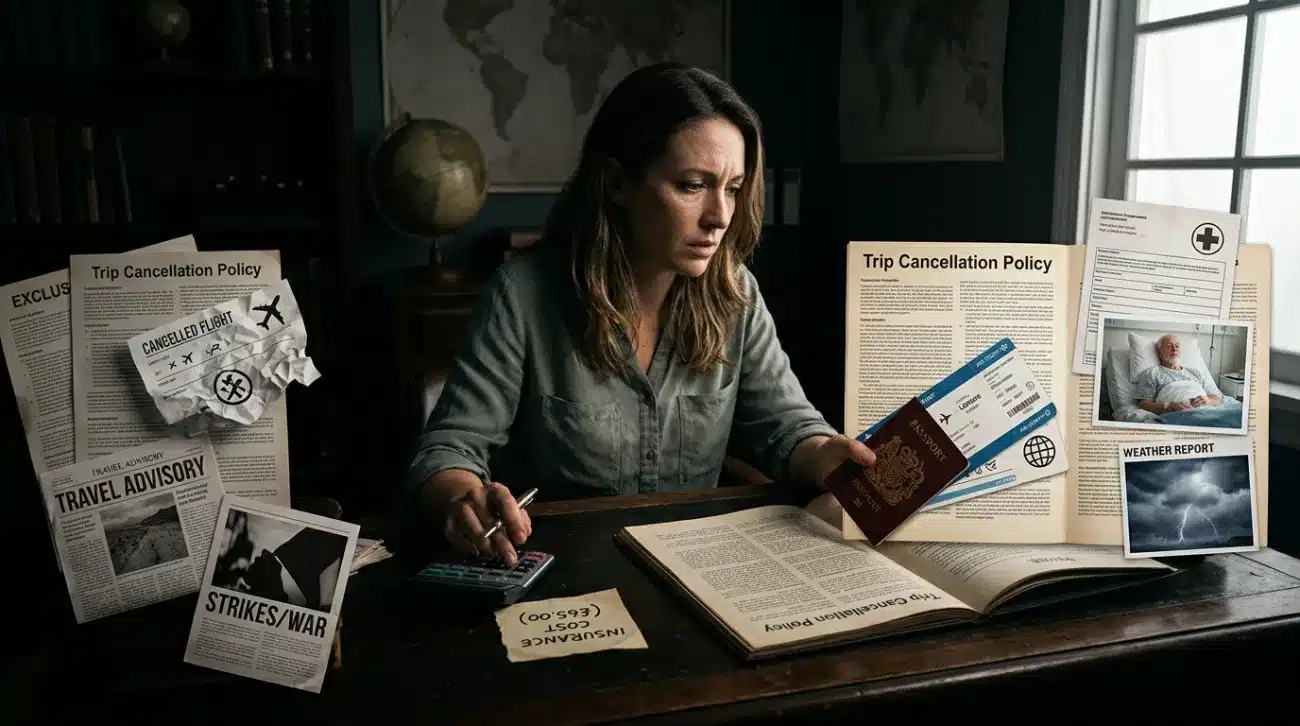
A policy is only worth what it will pay under the conditions you are most worried about. Covered reasons are spelled out in the contract, and the list differs by insurer and by plan. Exclusions are equally important. Policies commonly define what counts as a pre-existing medical condition, set conditions on when coverage must be purchased, and exclude certain events entirely. Whether a particular concern, such as a health issue, a family emergency, a work conflict or severe weather, is covered depends on the exact wording.
This is why timing and documentation matter. Many policies require that a cancellation be tied to a documented event, and some have deadlines that start from the date of the first trip payment. Travelers who assume that every disruption is covered may discover otherwise only after filing a claim. A careful reader will look for the definitions section, the exclusions list and the claim requirements before paying, because those pages decide whether the premium buys real protection or only the appearance of it.
Cruise Bookings and Other High-Stakes Trips
Cruises, group trips, international tours and holidays booked far in advance share a feature that makes the insurance question sharper: a large share of the cost is paid early and may become nonrefundable on a schedule set by the seller. Cruise lines and tour operators publish their own cancellation terms, and those terms determine how much of your payment is at risk at each stage of the booking. Reviewing the seller’s schedule alongside a policy’s terms shows where the real gap lies.
Long lead times add another consideration. The longer the gap between booking and departure, the more time there is for life to change, which is an argument some travelers cite for coverage. It is also a reason to confirm that the policy remains useful across that entire period. For trips tied to several travelers, it is worth checking how the policy treats a situation in which one person must cancel while others still go, since the effect on shared costs can vary by contract.
Lower financial exposure
Short trips with refundable bookings or inexpensive rebooking options. The potential loss is limited, so the case for a separate policy is generally weaker.
Moderate financial exposure
Trips with some nonrefundable elements, such as flights or lodging deposits. The decision turns on how much you could absorb if the trip fell through.
Higher financial exposure
Large prepaid trips such as cruises, tours or international journeys booked well ahead. More money is at risk, so reading policy terms closely carries more weight.
This breakdown is an editorial categorization for context. It is not measured data.